Get to know the content-powered agentic insurer
Learn how AI agents work with intelligent content platforms to automate routine decisions, instantly surface crucial information and accelerate claims resolutions from weeks to days.
Introduction
The insurance industry faces a persistent reality: Claims processing is slow, expensive and frustrating for everyone involved.
When a homeowner experiences a fire, their primary concern isn’t underwriting speed — it’s getting their loss assessed and approved quickly so they can rebuild. Yet, the standard property and casualty (P&C) claims process drags on for weeks. An adjuster must gather documents from multiple systems, manually review policy language, validate repair estimates, investigate potential fraud and coordinate with inspectors — all before a payment decision is made. For a policyholder experiencing a loss, waiting 15-20 business days feels like an eternity.
This isn’t just a customer satisfaction problem. It’s also a business efficiency issue. Claims staff spend their most valuable time on administrative tasks — hunting for documents across multiple systems, organizing information, checking policy provisions — rather than making decisions that require human judgment. Meanwhile, fraud indicators hide in plain sight, waiting for patterns that manual review can’t detect. And operational costs climb as staff manage processes that should be automated but aren’t.
This is the reality of traditional P&C claims operations. But a transformation is underway among forward-thinking carriers that have embraced what we call the content-powered agentic insurer. In this new operating model, AI agents work seamlessly with claims staff to automate routine decisions, instantly surface crucial information and accelerate claim resolutions from weeks to days.

The problem: P&C claims are drowning in unstructured data
A property claim is a clear example of the challenges associated with unstructured data. When a homeowner files a claim for fire damage, the adjuster’s workflow could involve:
Locating and reviewing policy documents to confirm coverage, identify exclusions and determine policy limits, which are often scattered across multiple systems
Gathering loss documentation from the claimant, fire department and contractors — a process that requires multiple requests and follow-ups
Reviewing repair estimates line by line to validate that they’re aligned with policy provisions and reasonable for the damage
Analyzing photos from multiple angles to understand the extent of the damage and identify potential coverage issues
Investigating possible fraud by cross-referencing prior claims, checking for suspicious patterns and validating claimant statements
Coordinating with contractors and inspectors to schedule inspections and resolve discrepancies
Documenting decisions in the claims system for compliance and audit purposes
Each step involves manual effort, context-switching between systems and waiting for responses. A “simple” property claim can take 10-15 business days. Complex claims with disputes can take months.
This creates a cascade of problems.
Glacial resolution times
Claimants experience lengthy waits before claims are approved. Contractors can’t begin restoration work. Families can’t move back into homes. Businesses can’t resume operations.
The human cost of delay is real.
Quality and consistency issues
Adjusters apply policy provisions inconsistently. One adjuster approves a damage assessment; another reviewing similar damage denies coverage. Medical expenses are questioned in one claim and approved in another.
The result is litigation risk, regulatory scrutiny and customer complaints.
Claims leakage
Overpayment or fraudulent claims can take a big hit on the bottom line. Detecting fraud requires analyzing patterns across claim details, photos, repair estimates and prior claim history. Preventing overpayment requires a comparison of the claim to policy coverage details. Manual task reviews simply can’t scale.
By the time fraud or overpayments are discovered, claims have been paid and losses realized.
Adjuster burnout
Experienced adjusters are often drowning in administrative work. They spend more time gathering documents and checking policy language than actually adjudicating claims.
Their valuable judgment skills should be spent on assessing complex damages, evaluating coverage disputes and making calls on edge cases — not searching for documents.
Customer frustration
Customers expect instant answers, but claim status inquiries can go unanswered for days. Customers call repeatedly asking the same questions. Satisfaction scores decline, retention suffers and the emotional toll of delayed resolution turns a difficult situation into a worse one.
The root cause: Unstructured content such as loss reports, repair estimates, photos, policy documents, inspection notes and contractor communications should enable rapid decisions. Instead, it’s scattered across systems, file types and formats, turning what should be a straightforward process into an administrative nightmare.
> Learn more: 7 ways agentic AI is transforming insurance
From Content To Intelligence: A Spotlight On Insurance
Forrester Consulting study examines AI agent adoption
Without the ability to unify, integrate and contextualize enterprise content, AI initiatives risk stalling at surface-level automation instead of driving meaningful business outcomes.
This study explores how leading insurers are scaling AI from pilots to enterprise-wide execution. You’ll find out where AI agents are delivering the most value and learn the key barriers to progress.
The solution: Content intelligence meets agentic automation
The content-powered agentic insurer flips this script by transforming claims content from a burden into a strategic asset. The model combines three capabilities that work together to accelerate claim resolutions:
Foundation: Hyland Enterprise Context Engine™
The Enterprise Context Engine structures your policy and claims data instantly.
Policy documents are indexed and linked to relevant claim information — ensuring coverage provisions are always accessible.
Loss documentation is analyzed claim by claim, extracting parties, coverages and loss details while validating against policy limits and claim history.
Claims adjusters’ notes and supporting documents are processed to identify relationships between claims, coverages, policies and parties.
Loss runs are organized and cross-referenced with historical data and coverage indicators.
The result: Your claim files aren’t scattered documents; they’re structured, AI-ready assets connected through your underwriting logic and linked to what each claim means in the context of your business.
Intelligence layer: Hyland Knowledge Discovery™
Next, your teams need rapid access to this structured intelligence. Knowledge Discovery — an AI-powered search and decision-support platform — enables grounded, explainable answers to complex business questions across multiple documents and topics.
An adjuster can ask, “What’s the policy limit and are there exclusions for this type of damage?” and immediately see relevant policy provisions.
A fraud investigator can ask if there are similar claims in the same area and see related cases instantly.
The result: Your team only needs seconds to search across multiple systems. Imagine reducing decision-making times from days to minutes. That’s the power of intelligent content discovery.
Automation layer: Hyland Agent Builder™ and Hyland Automate™
Finally, you can extend this intelligence into autonomous agents. Agent Builder enables you to configure AI agents that specialize in specific business tasks and operate with human supervision, and Automate gives you the power to configure and orchestrate multiagentic workflows or end-to-end processes.
These agents combine the enriched content with business logic to drive decisions.
A specialized claims agent can augment the judgment of an adjuster. The claims agent can validate coverage against policy provisions, compare damage to repair estimates, cross-reference prior claims for fraud signals and flag issues requiring human review. It generates a comprehensive claims assessment with supporting evidence — not to replace the adjuster’s decision, but to arm them with the information and analysis needed to decide quickly and accurately.
These three layers work together to create an operating model in which claims move from weeks to days, decisions are consistent and well-documented, fraud is identified before payment and adjusters focus on judgment-based decisions rather than information-gathering.
Real-world example: P&C homeowner fire claim
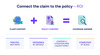
The scenario: A homeowner experiences a kitchen fire and files a claim immediately. Traditionally, the adjuster spends the next 20 business days hunting for information: locating the policy document to confirm the $200,000 dwelling coverage and fire provisions, requesting and reviewing repair estimates, scheduling an inspection, manually analyzing each line item against policy language, cross-checking prior claim history for fraud indicators and resolving edge cases. The edge case could be whether the homeowner receives replacement cost or actual cash value for marble countertops that replace the original laminate. During these four weeks, the homeowner remains displaced and reconstruction can’t begin.
With a content-powered agentic insurer, the process transforms.
On Day 1, the Enterprise Context Engine automatically structures all claim content: extracting key information from the loss report and photos, accessing the policy document to identify coverage limits and provisions, analyzing repair estimates against typical fire damage patterns and market rates, and cross-referencing 12 years of prior claims for fraud patterns. The claims agent delivers a comprehensive assessment to the adjuster — with coverage validated, estimates analyzed and fraud risk assessed — and flags one item for human judgment: the countertop replacement cost decision.
In the next couple of days, the adjuster makes that decision, authorizes payment and schedules the inspection. By Day 4, payment is released and the homeowner can begin reconstruction.
The impact: The adjuster reclaims their expertise. Instead of spending three weeks gathering documents and analyzing details, they spend one day making judgment calls and approving claims. The homeowner waits four days instead of 20. And the insurer can process four times the claims volume with the same staffing.
That’s the difference between traditional claims and agentic claims.
All of this is not autonomous decision-making. It’s providing decision support for your knowledge workers. And the results are happening within minutes, not days.
Why Hyland: Purpose-built for claim complexities
Claims processing is uniquely demanding. You manage regulated processes, handle sensitive personal data, require complete audit trails for every decision and operate at massive scale. Hyland’s content intelligence and automation platform is built for this.
Proven scale: Hyland is trusted by thousands of organizations, with proven technology handling billions of documents and transactions daily.
Governance and compliance: Our platform maintains full traceability and comprehensive logging to support auditable, compliant operations that secure sensitive data.
Diverse content types: Claims involve scanned policy documents, repair estimates, photos from multiple angles, contractor communications, inspection reports and prior claim history. Our enrichment technology handles more than 600 file formats while preserving context and relationships — from scanned estimates to construction photos to handwritten inspector notes.
Comprehensive platform: Unlike single-capability vendors, Hyland’s integrated platform combines content structuring, intelligent discovery and agentic automation to reduce complexity and accelerate implementation.
Adjuster-centric automation: Agent Builder doesn’t attempt to automate every claim decision; it augments adjuster judgment. The claims agent handles routine analysis and information synthesis, escalates exceptions and edge cases to adjusters, and provides comprehensive, evidence-based information to support faster decisions. Your adjusters remain in control of all coverage and payment decisions.
Transform your P&C claims operations
The P&C insurance landscape is shifting. Carriers that embrace content intelligence and agentic automation will dominate on speed, costs and customer experience. Those that don’t will be unable to compete on claims resolution turnarounds or operational efficiency.
The content-powered agentic insurer isn’t a future state — it’s achievable today. Implementation typically begins with a single line of business (auto, homeowners or commercial property) where the claims volume is the highest and the implementation risk is the lowest.
The transformation is substantial: Claims resolution times can drop from 15-20 days to 4-6 days, fraud detection shifts from post-payment investigation to real-time identification, and your adjuster team shifts focus from document hunting to judgment-based decisions. The results span your entire operation — improved cost structures, higher customer satisfaction and retention, reduced fraud losses, demonstrably compliant decisions and a more engaged team doing meaningful work.
Ready to transform your P&C claims operations? Contact us today or schedule a demo to see the content-powered agentic insurer in action.
Case Study
Fidelity United accelerates claims management with Hyland OnBase™
By combining automation, unified content management and streamlined workflows, the insurer is improving claims processing, increasing visibility and supporting better decision-making across the claims life cycle.
Article
Maximizing AI’s potential in P&C claims
Celent analyst Nathan Golia explores how leveraging AI can be sure-fire winner as insurers look to enhance their employee and customer retention.
Article
Insurance document management: From storage to intelligence
Explore how insurers can leverage AI to automate claims, accelerate underwriting and reduce regulatory risk.
Article
Getting to “yes” with AI adoption in insurance
AI adoption is moving at a blistering pace, but insurers want to see the time savings translate into headcount optimization, direct cost reduction or verifiable revenue.